 ultimate-guide
How to Interpret Financial Statements: A 2026 Guide
Table of Contents
- Why Interpreting Financial Statements Matters for Business Owners
- The Three Core Financial Statements Explained
- How to Read a Profit and Loss Statement
- Key Financial Ratios for Business Owners
- Common Financial Statement Red Flags to Watch
- How to Interpret Financial Data Over Time
- Building a Framework for Financial Decision-Making
- Frequently Asked Questions
Last Updated: September 25, 2026
Why Interpreting Financial Statements Matters for Business Owners
Understanding how to interpret financial statements is the difference between running your business on instinct and running it on data. Most business owners hand off their financial statements to an accountant once a year and never look at them again. These documents tell you exactly what's happening inside your business, where money is coming from, where it's going, and whether you're actually profitable.
The owners who understand their financial statements spot problems early, catch opportunities faster, and make confident decisions. When you can interpret financial statements, you stop relying on someone else's interpretation and start owning your business's financial reality.
Most guides treat financial statements like a textbook, defining terms and leaving you with zero clarity on what matters for your business. This guide shows you which numbers move the needle, what red flags to watch for, and how to use financial data to improve your bottom line.
The Three Core Financial Statements Explained
Every business produces three core financial statements that answer different questions about your financial health.
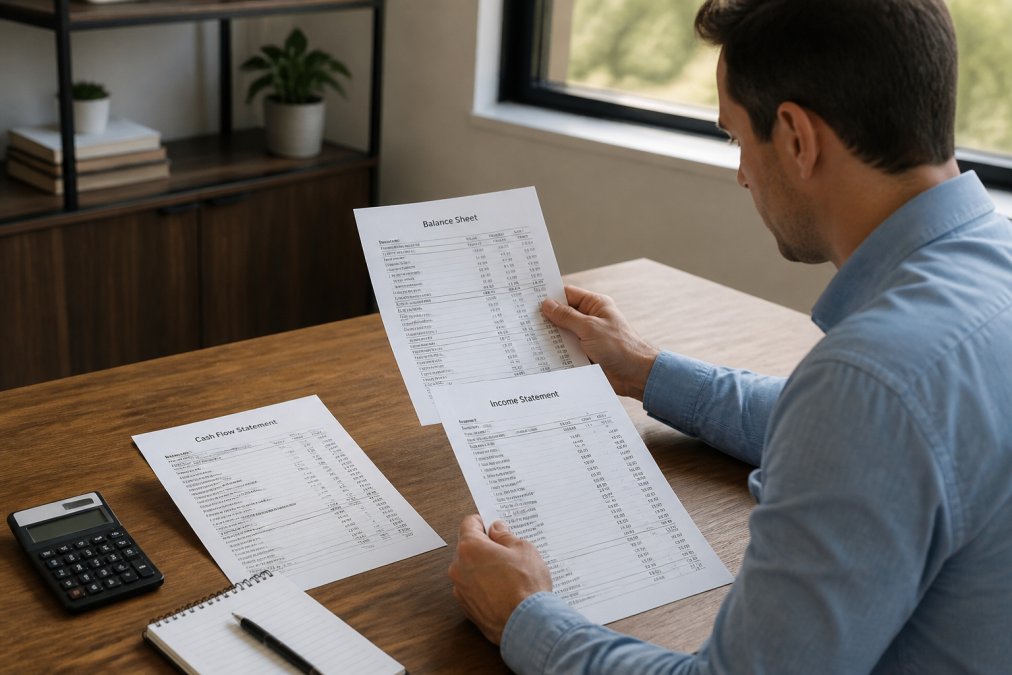
Balance Sheet: Assets, Liabilities, and Shareholders' Equity
A balance sheet is a snapshot of what your business owns and owes on a specific date. It balances: assets equal liabilities plus shareholders' equity.
Income Statement: Revenue, Expenses, and Net Income
An income statement shows how much money your business made and spent over a period of time, answering: did we make money or lose money?
Cash Flow Statement: Understanding Liquidity and Operations
A cash flow statement tracks actual cash movement in and out of your business. Unlike the income statement, it shows whether you can actually pay bills. You can be profitable on paper and still run out of cash.
How to Read a Profit and Loss Statement
A profit and loss statement is another name for an income statement. Reading it effectively means understanding the progression from gross profit to operating income to net income.
Gross Margin and Operating Expenses
Gross profit is revenue minus the direct cost of goods sold. Gross margin is gross profit divided by revenue, expressed as a percentage. For example, $100,000 revenue minus $40,000 cost of goods sold equals $60,000 gross profit and 60% gross margin.
EBITDA and Bottom-Line Profitability
EBITDA (earnings before interest, taxes, depreciation, and amortization) shows how much cash your business generates from operations before financing and accounting adjustments. Many business owners use it as a measure of operational profitability because it strips out non-cash expenses.
Key Financial Ratios for Business Owners
Financial ratios express relationships between numbers from your financial statements. They're tools for comparing your business to itself over time or to industry benchmarks.
Liquidity Ratios: Current Ratio and Working Capital
The current ratio divides current assets by current liabilities, showing whether you have enough short-term assets to cover obligations. Above 1.5 is healthy; below 1.0 is a warning sign.
Profitability and Solvency Ratios
Profit margin is net income divided by revenue, showing what percentage becomes profit. A 10% profit margin means you keep 10 cents per dollar. The trend matters more than the absolute number; declining margins signal revenue falling or expenses rising.
Schedule a FREE financial assessment today! →
Common Financial Statement Red Flags to Watch
Declining revenue with stable or rising expenses signals inflexible cost structure. Gross margin compression suggests lost pricing power or rising costs. Negative cash flow from operations despite positive net income means consuming cash, often from receivables growing faster than collections or inventory building faster than sales.
How to Interpret Financial Data Over Time
A single financial statement is a snapshot. Multiple periods tell a story. Interpreting financial data over time means looking at trends, understanding what's driving changes, and comparing your business to benchmarks.
Trend Analysis and Variance Analysis
Trend analysis compares financial metrics across multiple periods, quarters or years. You're looking for patterns. Is revenue growing or declining? Is gross margin stable or changing? Are operating expenses growing faster or slower than revenue? Trends reveal whether your business is moving in the right direction.
Industry Benchmarking and Context
Your financial ratios only matter in context. A 10% profit margin might be excellent in one industry and terrible in another. Benchmarking means comparing your ratios to industry averages. If your gross margin is 40% and industry average is 35%, you're doing better than average. If it's 25%, you're underperforming and need to investigate why.
Building a Framework for Financial Decision-Making
Interpreting financial statements is only valuable if it leads to better decisions. The best framework starts with asking the right questions.
| Financial Statement | Primary Purpose | Key Metrics | Time Period |
|---|---|---|---|
| Balance Sheet | Shows financial position | Assets, liabilities, equity | Point in time |
| Income Statement | Shows profitability | Revenue, expenses, net income | Specific period |
| Cash Flow Statement | Shows cash movement | Operating, investing, financing cash flows | Specific period |
Frequently Asked Questions
What are the three main financial statements and why do they matter?
The three main financial statements are the balance sheet, income statement, and cash flow statement. The balance sheet shows your assets, liabilities, and shareholders' equity at a specific point in time. The income statement displays revenue, operating expenses, and net income over a period. The cash flow statement tracks actual cash moving in and out of your business. Together, they reveal your financial health, profitability, and liquidity, critical for making informed business decisions and securing financing.
How do you identify red flags when reviewing a balance sheet?
Watch for declining assets without corresponding business growth, rising liabilities that outpace revenue, shrinking shareholders' equity, or unusual increases in accounts payable. A high debt-to-equity ratio signals excessive leverage. Unusual or unexplained changes in specific line items warrant investigation. Compare your current balance sheet to prior periods and industry benchmarks to spot trends. If current assets fall below current liabilities, your liquidity position may be at risk.
What is the difference between cash flow and profit on an income statement?
Profit (net income) is calculated using accrual accounting, which records revenue when earned and expenses when incurred, regardless of when cash changes hands. Cash flow measures actual money received and spent. A business can be profitable on paper but cash-poor if customers delay payment or inventory ties up capital. Depreciation and amortization reduce profit but don't affect cash. Understanding both is essential: profit shows operational success, while cash flow determines whether you can pay bills and fund growth.
How can business owners use financial ratios to measure performance?
Financial ratios compress complex data into meaningful metrics. The current ratio (current assets divided by current liabilities) measures short-term liquidity. Gross margin shows what percentage of revenue remains after direct costs. The debt-to-equity ratio reveals your capital structure and financial risk. Profitability ratios like return on assets or return on equity show how efficiently you generate earnings. Track ratios over multiple quarters and compare them to industry standards to identify trends, spot problems early, and benchmark your performance.
Why is it important to compare financial statements over multiple periods?
A single financial statement is a snapshot; trends emerge only over time. Comparing quarters or years reveals whether revenue is growing, whether expenses are controlled, and whether cash flow is improving or deteriorating. Trend analysis helps distinguish one-time events from structural problems. If gross margin is shrinking consistently, something has changed in your cost structure or pricing. Variance analysis, comparing actual results to forecasts, shows whether your assumptions were accurate and where to adjust strategy.
How do you read a P&L for dummies without an accounting background?
Start at the top with total revenue, then subtract cost of goods sold to find gross profit. Next, subtract operating expenses (salaries, rent, utilities) to find operating income. Finally, subtract interest and taxes to reach net income (the bottom line). The key insight: does more revenue reach the bottom line, or are expenses eating into profits? Look for unusual line items and compare each section to prior periods as a percentage of revenue. If your gross margin is 50% but industry average is 60%, investigate why.
What financial metrics should a small business owner track monthly?
Track cash balance, accounts receivable aging, gross margin percentage, operating expenses as a percentage of revenue, and net income. Monitor working capital to ensure you have enough cash to operate. Watch the debt-to-equity ratio and current ratio for liquidity health. Compare actual results to your forecast (variance analysis) to catch problems early. Review accounts payable to manage cash outflows. These metrics, reviewed monthly, give you early warning signals and help you steer the business with confidence.
How does industry context change how you interpret financial statements?
Different industries have vastly different financial profiles. Retail businesses typically have lower margins but higher asset turnover than professional services. Capital-intensive industries like manufacturing carry higher debt and depreciation. SaaS companies prioritize recurring revenue and customer acquisition costs differently than product-based businesses. A debt-to-equity ratio of 2.0 might be normal for a construction firm but risky for a consulting business. Always benchmark your ratios against industry peers and understand what's normal for your sector before drawing conclusions about your performance.